Research and Interviews
The Geothermal Inflection Point
SHARE


How Superhot Rock, firm electricity demand, public risk-sharing, and global knowledge networks could move next-generation geothermal from promising technology to strategic infrastructure
In an exclusive interview with GeoVanguard Intelligence, Terra Rogers, Senior Director for Superhot Rock Geothermal at the Clean Air Task Force, frames next-generation geothermal as approaching a decisive commercial and policy test. Once viewed largely as a geographically constrained renewable resource, it is now being recast as a potential source of clean, firm electricity for a grid facing rising—but still uncertain—demand from industrial electrification, digital infrastructure, and other power-intensive sectors.
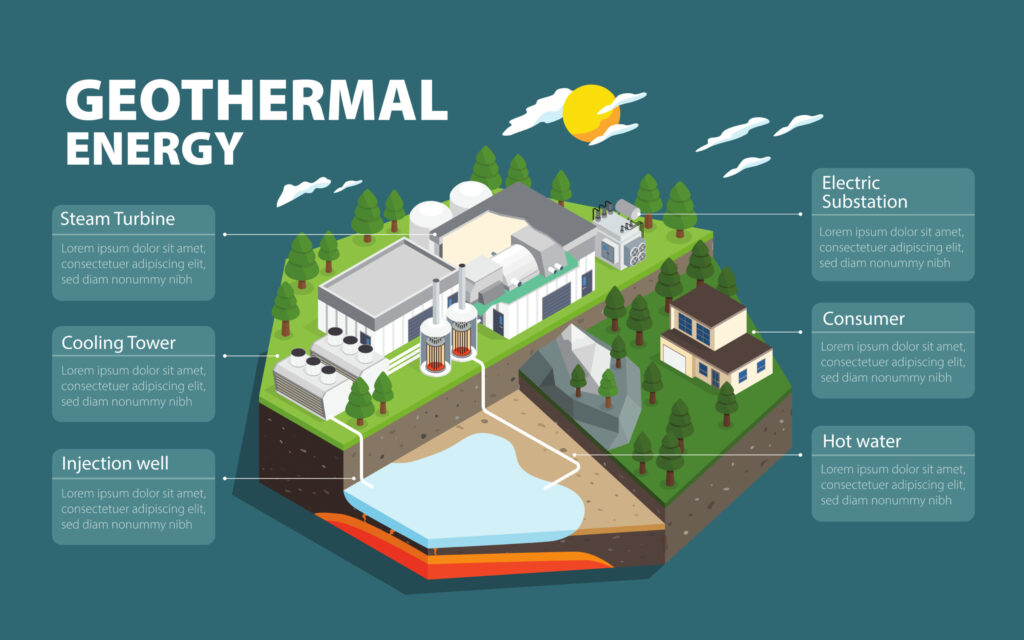
The industry’s long-standing constraints remain significant: subsurface uncertainty, capital intensity, immature supply chains, and the limited availability of naturally occurring hydrothermal reservoirs. Rogers’s argument is that these barriers are beginning to shift. Advances in drilling, reservoir stimulation, and high-temperature subsurface engineering are broadening the resource base, while large power users are increasing the value of clean, around-the-clock generation.
Her analysis presents the next phase not as a single-technology race, but as a systems challenge: connecting high-temperature subsurface innovation with public risk-sharing, oil-and-gas-scale execution capacity, specialized manufacturing, financeable project structures, and mechanisms that turn isolated technical lessons into collective industry capability.
This article examines five questions now shaping the market’s next phase: whether superhot systems can alter project economics, where durable demand will emerge, how supply chains can scale, what role governments should play in de-risking early basins, and how initiatives such as Geothermal Frontier can close the industry’s persistent knowledge gap.
Contents
Superhot Rock and the Economics of Higher-Enthalpy Power
For the geothermal industry, the move toward higher-enthalpy systems—particularly Superhot Rock formations around 400°C (750°F)—is not merely a technical milestone. Rogers framed it as an economic inflection point: hotter wells may cost more to drill, but their power output can rise much faster than their cost, improving the return profile of projects that would otherwise struggle to compete with other forms of firm power.
“The math is simple,” Rogers explained. “Yes, drilling a 400°C well is going to cost more than a 200°C well. But it is not going to cost five to ten times as much. However, it will produce five to ten times more power.”
This step change in energy density could materially alter the investment case. By engineering artificial reservoirs in dry high-temperature rock through next-generation technologies, developers are no longer limited to the geographic lottery of naturally occurring hydrothermal systems. Rogers argued that this technological shift could move the opportunity from a narrow set of favorable locations to a much broader global resource base.
Firm Power Demand and Geothermal’s Value Proposition
Rogers acknowledged that AI workloads, hyperscale data centers, and other power-intensive industries are contributing to an upward trend in electricity demand. She was careful, however, not to overstate the point: the direction of demand is rising, but its duration and ultimate scale remain uncertain.
That uncertainty does not remove the relevance of data centers; it clarifies the underlying point. For Rogers, the more durable issue is the need for reliable, always-on electricity. Solar and wind will remain central to decarbonized systems, but their variability makes them difficult to use as stand-alone solutions for customers that require continuous supply without substantial storage or complementary firm generation.
At present, many utilities are turning to natural gas to meet this baseload requirement. Rogers noted that this pathway carries several vulnerabilities, including exposure to fuel-price volatility, emissions constraints, and long lead times for key equipment such as gas turbines.
Rogers contrasted that pathway with geothermal’s ability to provide stable output without ongoing fuel exposure. She also emphasized its relatively small surface footprint, which could ease land-use tensions that often affect large-scale renewable deployment.
Industrial Scale-Up: The Supply-Chain Challenge Behind the Resource
Despite this potential, Rogers cautioned that the supply chain remains constrained by bespoke manufacturing, limited standardization, and the absence of a service ecosystem comparable to those supporting mature extractive industries.
To reach global scale, the technology will likely need the operational capacity of traditional oil and gas service companies such as SLB, Halliburton, and Baker Hughes. Rogers noted, however, that these firms remain heavily occupied with conventional projects amid persistent energy security concerns.
For Rogers, the key to mobilizing this capacity is not simply technological promise, but credible and coordinated policy signaling.
Rogers called for strong, unified signals from policymakers. If countries —which are beyond traditional geothermal markets—commit to incorporating the resource into a meaningful share of their energy mix, those signals could help justify the private investment required for service companies to adapt equipment, workforce, and operating models for geothermal applications.
In this context, Rogers also highlighted the role of international industrial capabilities. Japan, in particular, was cited for its manufacturing strength in high-tech production pumps and turbines. Rogers described this capacity as “phenomenal and second to none,” positioning Japanese suppliers as important potential contributors to the specialized equipment base required for scale-up.
From Exploration Risk to Bankable Infrastructure
Financing was another recurring theme. Rogers described a structural mismatch between the risk tolerance of commercial banks and the uncertainty profile of early-stage subsurface projects.
Commercial lenders typically seek stable, highly predictable revenue streams comparable to those of mature infrastructure assets. Early-stage greenfield EGS projects, by contrast, carry subsurface uncertainty that can make conventional project finance difficult to access until sufficient field data has been generated.
To bridge this “Valley of Death” between pilot demonstrations and commercially bankable assets, Rogers argued that governments must absorb the “first-in-basin” risk: the uncertainty and cost concentration that arise when developers drill the first wells in a basin before enough subsurface data exists to support conventional project finance.
The first wells in a new basin are typically the most expensive because operators are still learning the local geology, drilling conditions, and reservoir response. In a multi-well development, costs can decline materially as teams move from appraisal to repeatable execution. Public funding, shared testbeds, grants, and loan guarantees can therefore play a catalytic role in moving projects beyond the highest-risk phase.
Rogers pointed to the U.S. government’s Utah FORGE program as a model for this approach. By taking a greenfield site, proving the region’s technical viability, and making subsurface data publicly available, the program reduced information asymmetry for private developers and helped convert public risk-taking into broader commercial value.
She also emphasized the potential value of government-backed reinsurance mechanisms. By helping absorb early subsurface risk, public programs could encourage insurers to enter the market, accumulate data, and develop a more accurate understanding of geothermal risk profiles. Once initial basins are better characterized, commercial banks may be more willing to finance subsequent development.
Geothermal Frontier and the Case for Shared Technical Intelligence
Rogers observed that geothermal has historically operated in fragmented knowledge silos. Unlike oil and gas, where service companies routinely move across projects and operators, the field has had fewer channels for systematically transferring operational lessons, bench-scale findings, and field data across regions.
This fragmentation was one motivation behind Geothermal Frontier, a CATF-supported effort to make global expertise more discoverable. Rogers described it as a response to a practical gap: researchers, geochemists, developers, and equipment designers often need to know who has tested specific rocks, fluids, temperatures, or geochemical conditions, but that knowledge is difficult to locate across institutional and national boundaries.
The platform is designed for two overlapping audiences. One is the technical practitioner—for example, a geochemist or project engineer who needs data on how geothermal fluids interact with particular rock types at 300°C, 400°C, or higher temperatures before designing surface equipment. The other is the research community, where laboratories may possess complementary capabilities but lack an efficient way to identify potential collaborators.
Rogers linked the initiative’s urgency to the emergence of projects such as Mazama and Quaise, which are pursuing EGS at significantly higher temperatures. Her point was that the industry should not force every developer to learn only through costly field trials several kilometers underground. Better access to bench-scale expertise, geochemical data, and international research networks could help teams iterate faster before committing capital in the field.
For Japan, this theme carries particular strategic relevance. Rogers pointed to Japanese expertise in brittle-ductile research and high-temperature geoscience as an important but under-diffused knowledge base. If that expertise can be translated, connected, and made visible to global developers, Japan could contribute not only manufacturing capacity, but also technical intelligence that shapes the next generation of geothermal deployment.
Conclusion: Turning Subsurface Heat into Strategic Infrastructure
Next-generation geothermal is emerging as a strategic infrastructure option for economies that need clean, firm, and scalable electricity. Rogers’s perspective makes clear that the opportunity is not defined by geology alone, but by the alignment of drilling innovation, public risk-sharing, supply-chain mobilization, demand from power-intensive sectors, and knowledge-sharing initiatives such as Geothermal Frontier.
The remaining challenge is execution. Superhot Rock and advanced EGS technologies must prove that they can move from individual demonstrations to repeatable, financeable portfolios. That transition will require governments to underwrite the first wells, manufacturers to scale high-temperature equipment, insurers and banks to learn from transparent field data, developers to collaborate more openly, and technical communities to make hard-earned subsurface knowledge easier to find and apply.
If those conditions converge, deep geothermal heat can become more than a niche clean-energy solution. It can become one of the few resources capable of delivering round-the-clock, low-carbon power with a small land footprint and a global addressable market. In that sense, the next geothermal boom will not be won only underground; it will be won through policy confidence, industrial coordination, and the ability to turn subsurface heat into bankable energy infrastructure.
Free Membership Registration
What You Can Do After Registering
All articles are available to read free of charge. Free membership registration is required to download reports.
- You can download all reports that we make available free of charge in the future.
- You can opt in to receive our newsletter (the launch date and frequency will be determined at a later date).

This is a Japanese-English bilingual media outlet specializing in geothermal energy, operated by GeoVanguard Energy Inc. Information from Japan tends to stay within Japanese, while overseas information does not reach Japan. Our purpose is to bridge that gap.